

Could a lower monthly payment end up costing more over time? When considering financing for cosmetic procedures, it’s understandable to focus first on what fits your monthly budget. Interest, fees, promotional terms, and repayment timelines can change the full picture.
The right option depends on more than the payment amount. Healthcare credit cards, personal loans, and installment plans can work differently, and a promotional offer may come with conditions that affect what you repay. Understanding those details can help you compare choices without taking on a commitment that strains your budget.
This guide explains how common financing routes differ and what to review before accepting an offer, including total repayment, interest terms, fees, and credit inquiries. At Reviive Lounge Aesthetics, personalized, education-first treatment planning can help you discuss your aesthetic goals and budget considerations so you can make an informed decision without pressure.
Key Takeaways
- Compare financing for cosmetic procedures by looking beyond the monthly payment to the full repayment timeline and terms.
- Learn how healthcare credit cards and installment plans differ, and why promotional language matters.
- Use lender disclosures to distinguish deferred interest from a genuine zero-interest offer before accepting terms.
- Build a practical pre-application checklist around treatment priorities, essential expenses, existing obligations, and a repayment plan.
- Explore how personalized treatment planning at Reviive Lounge can include a thoughtful discussion of goals and budget considerations.
Financing for Cosmetic Procedures: What to Consider Before Choosing
Cosmetic-procedure financing spreads payments for an eligible treatment over time under terms set by a lender or payment-plan provider. Those terms vary by offer. Review the agreement that applies to you rather than assuming every financing route has the same eligibility requirements or repayment structure.
It’s easy to focus on a monthly payment when an offer is presented that way. But that figure alone doesn’t show the full repayment obligation or whether the schedule fits your finances. Treat the decision about treatment and the decision about payment as separate steps. You can explore your treatment goals first, then compare payment choices without letting an available plan determine what care you choose.
Why the monthly payment is only one part of the decision
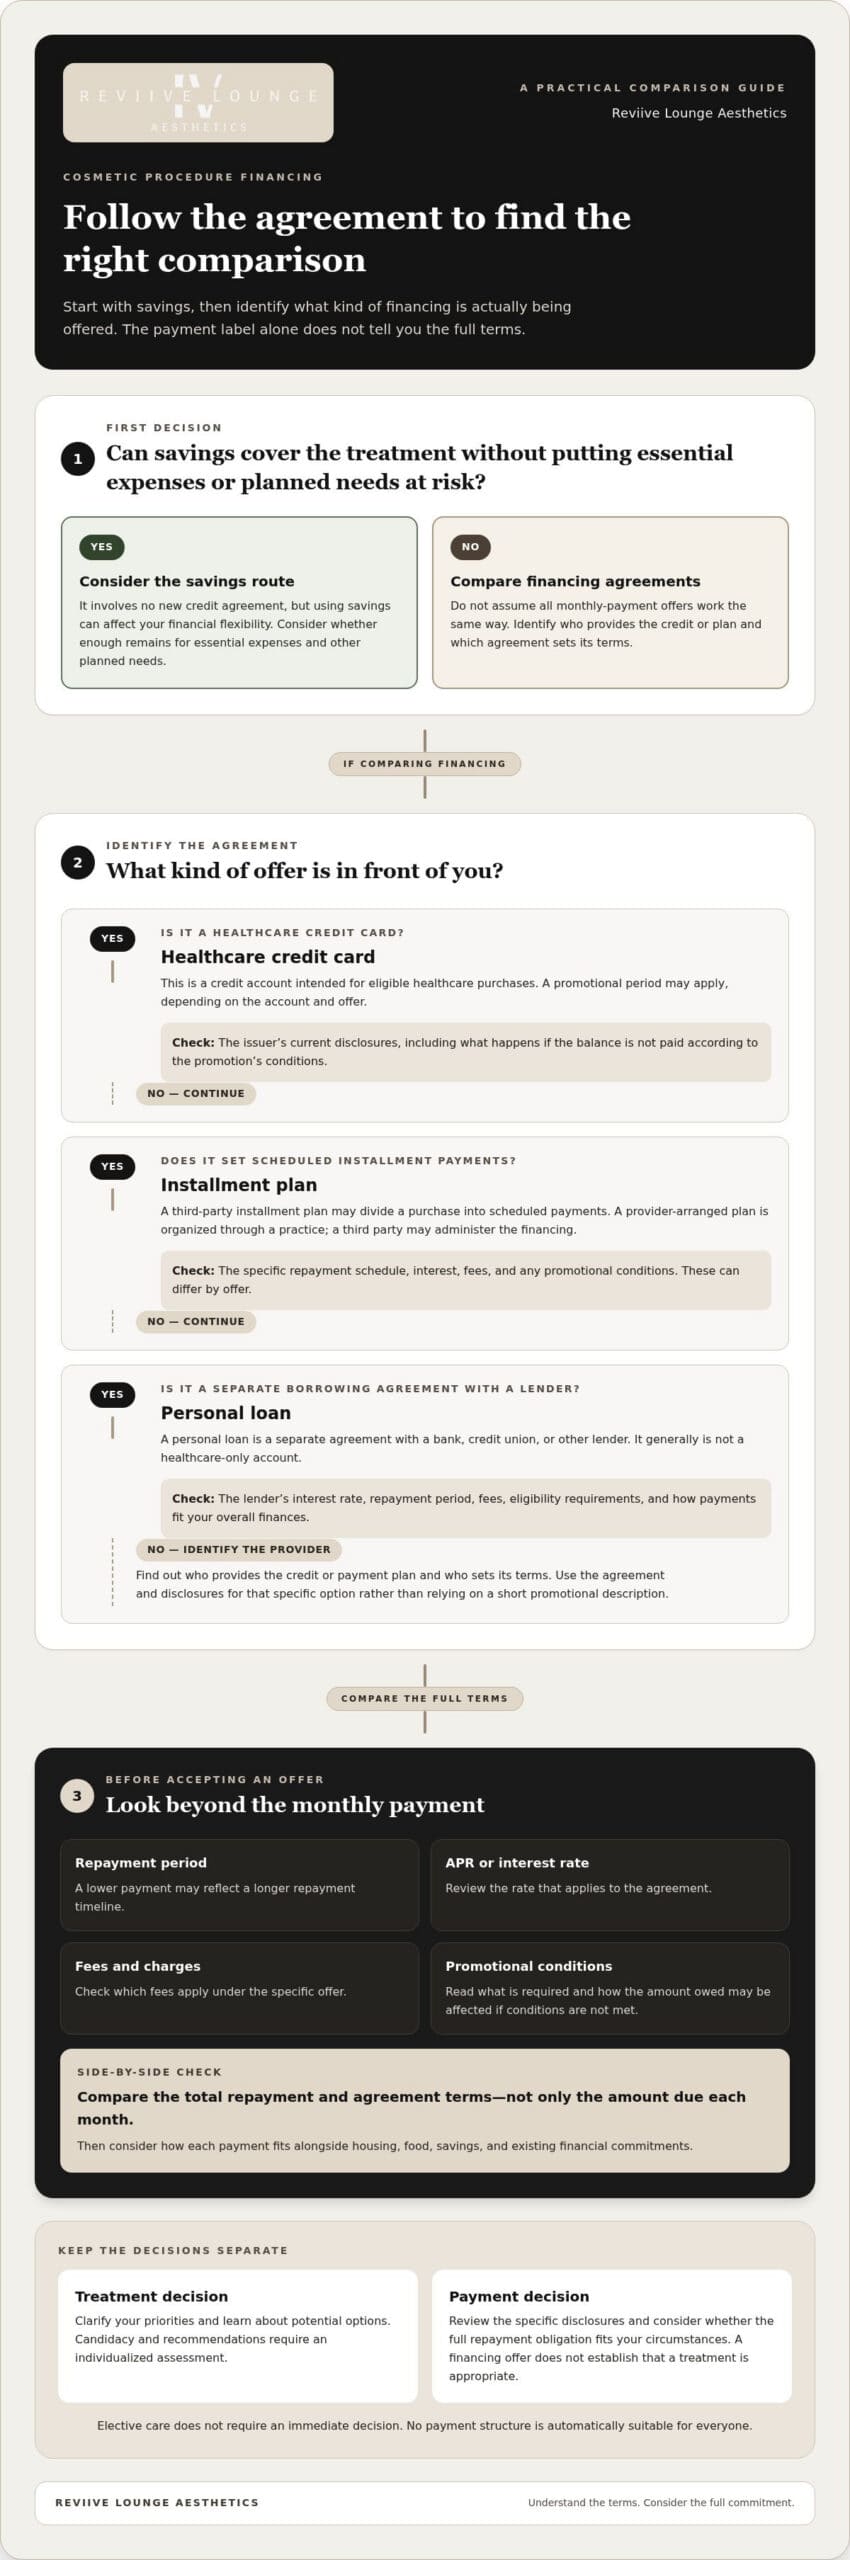
A payment amount only makes sense alongside the length and conditions of the agreement. Before accepting financing for cosmetic procedures, review the repayment period, APR or interest rate, applicable fees, and any promotional conditions. A lower payment may reflect a longer repayment timeline. A promotional offer may include requirements that affect the amount owed if its terms aren’t met. Read the current lender disclosures and consider the total obligation, not just what is due each month.
For example, two offers with similar monthly payments could have different repayment periods or interest terms. Compare them side by side, then consider how each payment would fit alongside housing, food, savings, and existing financial commitments. No payment structure is automatically comfortable or suitable for everyone.
How personalized treatment planning fits the decision
Start with your priorities: what you hope to address, which options you’re curious about, and what you’d like to understand before deciding. Cosmetic treatments vary, and a general Cosmetic Surgery Overview can provide background on the broader field without determining which treatment is right for you.
At Reviive Lounge, an education-first, personalized consultation is an opportunity to discuss your goals and learn about potential treatment options. Candidacy and recommendations require an individualized assessment; a financing offer doesn’t establish that a treatment is appropriate. Keeping those conversations distinct can help you make a considered choice about care and payment, without pressure to proceed.
- Clarify your treatment priorities before reviewing payment offers.
- Read the current disclosures for the specific financing option.
- Consider the full repayment obligation alongside essential expenses and existing commitments.
Understanding both decisions creates a more informed starting point. First consider whether a treatment aligns with your goals. Then assess whether its payment terms fit your circumstances before making a commitment.
Common Financing Options for Cosmetic Procedures, Explained
Payment routes for aesthetic care can include borrowing from a lender, a third-party financing plan, a practice-arranged plan, or personal savings. These options aren’t interchangeable. To compare financing for cosmetic procedures, identify who provides the credit or payment plan and who sets its terms. That distinction helps you locate the agreement, disclosures, and repayment details that apply to your situation.
Healthcare credit cards and third-party payment plans
Healthcare credit cards, such as CareCredit or Alphaeon Credit, are credit accounts intended for eligible healthcare purchases. Depending on the account and offer, a promotional period may apply. Read the issuer’s current disclosures, including what happens if the balance isn’t paid according to the promotion’s conditions.
Third-party installment plans, such as those associated with Cherry, may divide a purchase into scheduled payments under the plan’s terms. Their structure can differ from a revolving credit card. The repayment schedule, interest, fees, and promotional conditions depend on the specific offer. A provider-arranged installment plan is organized through a practice, while a third party may administer the financing. Don’t assume that “monthly payments” means the same thing across these arrangements.
Before applying, review the actual agreement rather than relying on a short promotional description. Note the payment schedule, total repayment, applicable charges, and conditions for any introductory offer. Current lender disclosures are the reference for terms and eligibility.
Personal loans and paying from savings
A personal loan is a separate borrowing agreement with a bank, credit union, or other lender. The lender defines its interest rate, repayment period, fees, and eligibility requirements. Because it generally isn’t a healthcare-only account, compare the complete loan terms and consider how scheduled payments would fit your overall finances.
Using savings avoids a new credit agreement, but it still affects your financial flexibility. Consider whether setting aside funds for a discretionary treatment would leave enough for essential expenses and other planned needs. Elective care doesn’t require an immediate decision. Avoid relying on emergency funds or taking on payments that feel difficult to manage.
A simple comparison can clarify the trade-offs: a credit card may have revolving terms, an installment plan may specify scheduled payments, a personal loan follows a separate lender agreement, and savings involve no new borrowing. None is automatically the best choice for everyone. Compare current disclosures with your circumstances before deciding.
If you’d like to discuss treatment goals and budget considerations in a personalized, education-first setting, learn about Reviive Lounge and its approach to aesthetic care.
How to Compare Cosmetic Procedure Financing Beyond the Monthly Payment
Compare each offer using the same details from its current written disclosures. A side-by-side view can reveal differences a headline payment may conceal, including how long you’ll repay and what could happen if you miss a payment or don’t meet a promotional condition.
Which financing terms should you compare?
Record the lender or provider, repayment period, APR, fees, and total repayment for each option. Include late-payment conditions and promotional deadlines. If a term isn’t stated clearly, use the lender’s agreement and disclosures to understand what applies rather than assuming there is no cost or condition.
| Provider | Repayment period | APR | Fees | Total repayment |
|---|---|---|---|---|
| Healthcare credit card issuer | Enter the period stated in the offer | Enter the disclosed APR and promotion terms | Record any disclosed charges | Use the lender’s repayment details |
| Installment-plan provider | Enter the scheduled term | Record the offer-specific APR | Include applicable disclosed fees | Calculate from the written offer |
| Personal-loan lender | Enter the loan term | Record the stated APR | Include applicable disclosed fees | Use the lender’s full repayment schedule |
Pay close attention to the difference between deferred interest and a genuine 0% APR offer. With deferred interest, the agreement may require you to pay the promotional balance in full by a stated deadline to avoid interest charges described in the disclosure. A true 0% APR offer means no interest is charged during the specified period under its terms, though other conditions may still apply. Read the lender’s wording rather than relying on phrases such as “interest-free” or a sample monthly payment.
Promotional claims are specific to an offer and can change. Verify current figures, eligibility conditions, and repayment rules in the applicable disclosures before comparing financing for cosmetic procedures.
How to assess credit and application considerations
An initial eligibility check and a formal credit application may involve different steps. Some lenders may offer an initial review that doesn’t affect a credit score, while a formal application may involve a credit inquiry. Check the lender’s current explanation of the inquiry and how it may appear on your credit file before proceeding.
Approval and available terms depend on the lender and the individual application. A comparison table or advertised example can’t predict your result. Before submitting an application, confirm whether it is an eligibility check or a formal application and review the stated credit-check details. Base your decision on the offer presented to you, not a promotional example that may not reflect your terms.
A Responsible Budgeting Checklist Before You Apply
Preparing for an application starts with your priorities, not the amount a lender may offer. Setting a personal limit can help you decide whether financing for cosmetic procedures fits your circumstances, without treating an available payment plan as a reason to move forward.
Use this checklist to organize your thinking before you apply:
- Clarify treatment priorities. Identify what you’d like to discuss and which goals matter most. A consultation can help you understand potential options, but it doesn’t obligate you to proceed.
- Set a payment boundary. Decide what, if any, recurring payment could fit your budget before reviewing offers. Include the total repayment obligation, not only the monthly amount.
- Review essential expenses and existing commitments. Consider housing, utilities, food, transportation, savings goals, and payments you already owe. A new obligation shouldn’t come at the expense of needs you rely on.
- Read the complete financing terms. Look beyond promotional language to the APR, fees, payment schedule, promotional conditions, and consequences of a late or missed payment.
- Map out repayment. Consider how payments would fit into your regular budget over the full term, including any changes after an introductory period.
If the numbers feel tight or uncertain, pause. There’s no need to borrow beyond your means or use funds set aside for essential needs. This checklist is a planning tool, not individualized financial advice; your circumstances and comfort level are personal.
Set a payment boundary that fits your finances
Choose your boundary before an offer’s monthly figure influences your expectations. Consider the payment alongside the full repayment amount and your other obligations, then decide whether it leaves your budget workable. A longer term or a lower initial payment doesn’t automatically make an offer a better fit. Financing being available doesn’t mean you need to use it.
Questions to resolve before accepting an offer
Before signing, make sure you can find clear answers in the complete agreement or the lender’s current disclosures:
- What APR applies, and can it change under the offer’s terms?
- Are there fees, and what is the complete repayment schedule?
- What happens if a payment is late or missed?
- If there’s a promotion, what conditions apply and what happens to any unpaid balance when it ends?
If any term is unclear, ask the lender for an explanation before accepting the offer. Keep the financial decision separate from clinical suitability: approval doesn’t determine whether a treatment is appropriate, and a consultation doesn’t promise a particular outcome. At Reviive Lounge, an education-first conversation can help you explore treatment goals and budget considerations without pressure. Explore treatment planning at Reviive Lounge.
Discuss Cosmetic Treatment and Financing at Reviive Lounge in Chino
Reviive Lounge is a physician-led medical aesthetics and wellness practice in Chino. Treatment planning begins with understanding the person, not selecting a payment option. Flexible financing options are available, and a personalized, education-first consultation offers space to discuss your goals, learn about potential treatments, and consider budget questions without pressure to proceed.
Financing and clinical decisions serve different purposes. A payment option doesn’t determine whether a treatment is appropriate, and a consultation doesn’t require you to accept financing or move forward with care. Keeping those choices distinct can help you assess each on its own merits.
Connect your treatment goals with a personalized consultation
Start by describing what you hope to address and what you’d like to understand. A clinical assessment helps determine which options may suit your individual needs; recommendations depend on that conversation and your circumstances. If you’re exploring neurotoxin treatment, the Botox injections guide for Chino offers additional context about the practice’s aesthetic injectables and neurotoxin options.
A useful consultation can help you sort through questions such as:
- Which treatment options align with the goals you’ve described?
- What should you understand about the recommended approach before deciding?
- What budget considerations or financing questions would you like to discuss?
These questions support an informed conversation, not a predetermined outcome. Your clinician can discuss treatment considerations based on an individualized assessment, while you can separately review whether any payment arrangement fits your financial circumstances. No financing decision can promise a particular aesthetic result.
Take a low-pressure next step
Before your consultation, consider bringing a short list of priorities and any questions about payment schedules, written terms, or how to compare offers. You don’t need to arrive with a financing decision already made. Taking time to understand the treatment discussion and payment considerations can help you decide what, if anything, feels right for you.
At Reviive Lounge, the conversation centers on education and personalized planning. You can explore treatment options, discuss budget considerations, and take time to weigh your choices. Flexible financing may be part of that discussion, but it doesn’t create an obligation to apply or proceed with treatment.
If you’re ready to discuss your goals and questions in a consultation, Schedule a consultation at Reviive Lounge.
Choose a Next Step That Feels Right for You
You don’t have to make every decision at once. Give yourself room to reflect on what you hope to achieve, what questions remain, and whether a payment commitment feels appropriate for your circumstances. A thoughtful decision about financing for cosmetic procedures should support your broader priorities, not compete with them.
If you’re ready to explore treatment possibilities, a conversation can help you clarify what you’d like to discuss and consider your next steps at your own pace. There’s no need to arrive with every answer or a financing decision already made.
Reviive Lounge is located in Chino and welcomes clients from nearby communities, including Norco, Corona, Chino Hills, Rancho Cucamonga, Ontario, Eastvale, Pomona, La Verne, Upland, and Fontana. Schedule a consultation at Reviive Lounge to discuss your goals and treatment options. Move forward with care and clarity, at a pace that feels right for you.
Frequently Asked Questions
Can you finance Botox or other cosmetic injections?
Financing for cosmetic procedures depends on the lender, the terms of the offer, and treatment eligibility. Reviive Lounge offers flexible financing options, but approval and the terms that apply to a particular service depend on the financing offer. Review the current terms and repayment obligations before applying. An individualized consultation can help you discuss whether an injection may suit your goals, separately from deciding how to pay.
Does applying for cosmetic procedure financing affect your credit score?
It may, depending on the lender and whether you’re completing an initial eligibility check or a formal application. A preliminary review and a full credit application may involve different inquiry procedures. Before submitting personal information, read the lender’s current disclosure to learn whether an inquiry may be reported and what type it is. The effect can vary by individual, so no general statement can predict a specific credit-score change.
Is cosmetic procedure financing the same as a zero-interest payment plan?
No. A 0% APR offer and a deferred-interest promotion can have different conditions. With deferred interest, the agreement may state that interest applies if you don’t meet the promotional payoff requirements. A zero-interest offer also has specific terms, such as a defined promotional period. Before accepting, read the full agreement for the APR after any promotion, fees, payment requirements, and what happens to an unpaid balance.
Can you use a healthcare credit card for more than one cosmetic treatment?
Possibly, if the card issuer’s rules permit those purchases, the treatments qualify, and enough credit is available. A card may be limited to eligible services, so review your account agreement and issuer information before planning multiple services around one card. Keep track of separate charges and how each may affect your balance and payment obligations.
How much should I budget each month for cosmetic procedure financing?
There isn’t one monthly amount that fits everyone. Your payment depends on the treatment plan, the financing offer’s repayment period and terms, and your existing financial commitments. Consider a personal budget that includes routine expenses, current debt payments, and savings priorities before deciding whether a recurring payment feels manageable. A treatment discussion can clarify the proposed scope, while the lender’s written offer provides the figures needed to assess its payment schedule.
Can I combine savings with financing for a cosmetic procedure?
Some people consider using more than one payment source, but whether savings can be combined with a financing offer depends on the lender’s terms and the payment arrangements. Your own needs matter, too. Using savings may affect funds reserved for other priorities, so review the agreement and consider your broader budget before choosing a mix. There’s no universal amount of savings or borrowing that’s appropriate for everyone.
What should I do if I am not approved for cosmetic procedure financing?
Start by reviewing the lender’s explanation and any information it provides about the decision. You can pause, reconsider treatment priorities, or set aside savings over time rather than immediately applying for another loan. If you revisit treatment planning, an individualized consultation can help you discuss options separately from financing approval. A declined application doesn’t determine clinical suitability, and it’s reasonable to wait if another payment commitment wouldn’t fit your budget.